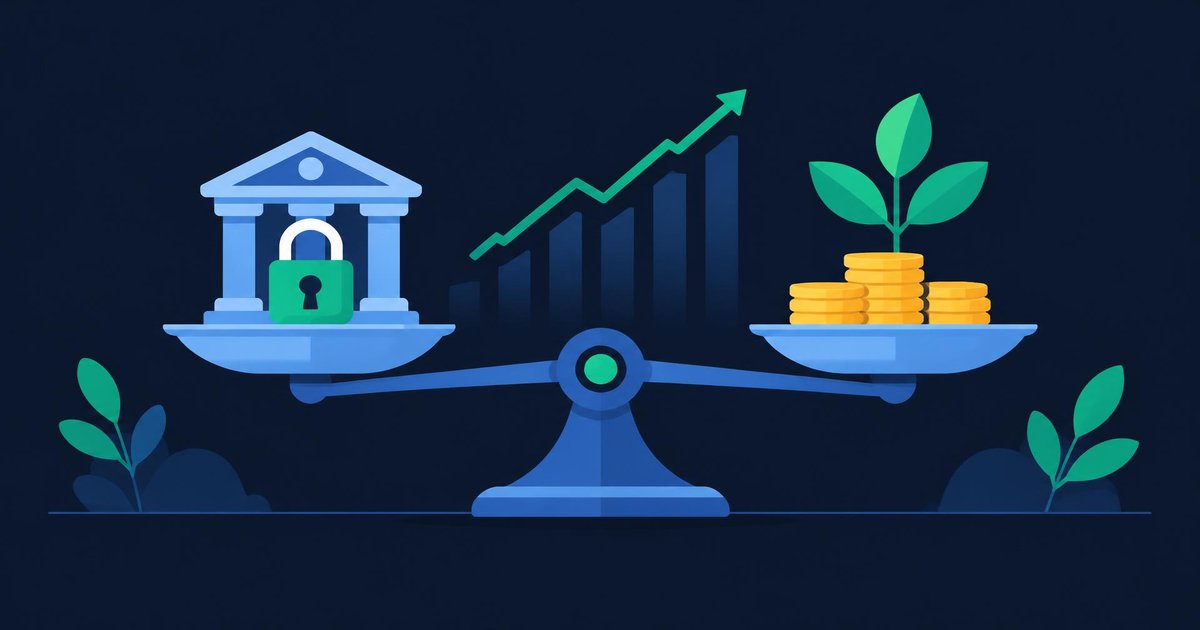
It is the most common investing question in Indian households: should the money go into a fixed deposit, where it is safe, or into a mutual fund, where it can grow? The honest answer is that they are not rivals — they do different jobs. This guide compares them head to head so you can decide which job your money needs to do.
The Core Difference in One Line
A fixed deposit lends your money to a bank at a guaranteed interest rate. A mutual fund invests your money in stocks, bonds or both, with no guarantee but far more growth potential.
Head-to-Head Comparison
| Feature | Fixed deposit | Equity mutual fund |
|---|---|---|
| Returns | Fixed, known in advance | Market-linked, variable |
| Risk | Very low (deposit insurance up to ₹5L per bank) | High in short term, lower over long horizons |
| Inflation protection | Weak after tax | Strong over long periods |
| Liquidity | Penalty on premature withdrawal | Redeemable anytime (exit load may apply early) |
| Lock-in | Chosen tenure | None (except ELSS: 3 years) |
| Tax | Interest taxed at your full slab every year | Gains taxed only on redemption, at lower capital-gains rates |
| Income option | Regular interest payouts | SWP (systematic withdrawal plan) possible |
The Tax Gap Most People Miss
This is where FDs quietly lose. FD interest is added to your income and taxed at your full slab rate — every single year, even if you do not withdraw it. In the 30% slab, a 7% FD effectively yields under 5% after tax.
Equity mutual funds are taxed only when you sell, and as long-term capital gains (held over a year) at 12.5% on gains above ₹1.25 lakh a year. Your money compounds without an annual tax leak. Use our Tax Calculator to see your own slab''s impact.
The Inflation Problem
If your FD earns 7% and inflation runs at 6%, your real growth is about 1% — before tax. After tax in a high slab, you may be standing still or going backwards in purchasing power. Equity mutual funds are volatile, but over 10–15 year periods Indian equities have historically beaten inflation by a wide margin. That is why the two products answer different questions:
- FD question: "Will my money be there, exactly, when I need it?" — Yes.
- Mutual fund question: "Will my money grow meaningfully over the years?" — Historically, yes, with bumps along the way.
When a Fixed Deposit Is the Right Choice
- Emergency fund. Money you might need tomorrow must not be in equities.
- Goals within 1–3 years. A wedding next year, a car down payment in 18 months — certainty beats growth here.
- Retirees needing predictable income with zero appetite for market swings.
- Parking money temporarily while you decide where to deploy it.
When Mutual Funds Are the Right Choice
- Goals 5+ years away — retirement, children''s education, wealth building.
- Beating inflation over decades, not months.
- Monthly investing (SIP) — you cannot easily SIP into an FD, but SIPs make equity volatility work for you through rupee-cost averaging. Try our SIP Calculator to see the long-term math.
- Tax-efficient growth for anyone in the 20–30% slabs.
A Sensible Middle Path: Use Both
Most Indian households are best served by a split, not a winner:
This way a market crash never forces you to break a goal, and inflation never quietly eats your future.
What About Debt Mutual Funds?
Between FDs and equity funds sit debt mutual funds — they invest in bonds and aim for FD-like stability with better tax treatment on long holdings. They are not risk-free (interest rates and credit events affect them), but for money parked 3+ years they can be more tax-efficient than an FD. If you are comparing, also read our index fund guide for the simplest equity option.
FAQs
Are mutual funds safer than FDs?
No. FDs carry deposit insurance up to ₹5 lakh per depositor per bank and a guaranteed rate. Mutual funds carry market risk and no guarantee. Safety is the FD''s home ground — growth is the mutual fund''s.
Can I lose all my money in a mutual fund?
In a diversified equity fund, losing everything is extremely unlikely — it would require the entire market of large companies to fail. Real losses of 20–40% in a bad year are possible, which is why equity funds suit long horizons where recoveries have time to happen.
Which gives better returns — FD or mutual fund?
Over short periods, either can win. Over long periods (10+ years), diversified equity mutual funds have historically outpaced FDs by a wide margin, especially after tax. Past performance does not guarantee future results.
Is FD interest taxable?
Yes, fully — at your income-tax slab, every year as it accrues. Banks also deduct TDS once interest crosses the applicable threshold. This annual tax drag is the FD''s biggest hidden cost.
Should I break my FDs and move everything to mutual funds?
No. Keep your emergency fund and short-term goal money in FDs. Only money earmarked for goals 5+ years away belongs in equity mutual funds.
What is better for monthly investing?
Mutual funds, clearly. A SIP automates monthly investing and turns market volatility into an advantage. FDs require a fresh deposit each time at whatever rate the bank offers that day.
Sources and Update Note
This comparison was written on 10 October 2026 using the Income Tax Act provisions applicable for FY 2026-27 and publicly available information from Indian banks, SEBI and AMFI. We intentionally avoid quoting specific FD rates or fund returns, which change frequently — check current rates with your bank and the latest fund factsheets before deciding.
Important Disclaimer
This article is for education only and is not investment or tax advice. Mutual fund investments are subject to market risks. Read all scheme-related documents carefully and consult a SEBI-registered investment adviser for advice tailored to your situation.
Did you find this useful?