Arbitrage Funds Explained: Low-Risk, Tax-Efficient Parking for Your Money in India
You have ₹5 lakh sitting in a savings account earning around 2.5–3% interest. You do not want stock-market risk, but you also do not want inflation quietly eating your money. This is exactly the gap arbitrage funds were built to fill.
Arbitrage funds are a type of hybrid mutual fund that earns money from tiny price differences of the same stock between two markets — and because SEBI classifies them as equity funds, they enjoy equity taxation. That combination of low risk plus tax efficiency makes them one of the smartest parking spots for short-term money in India.
What Is an Arbitrage Fund?
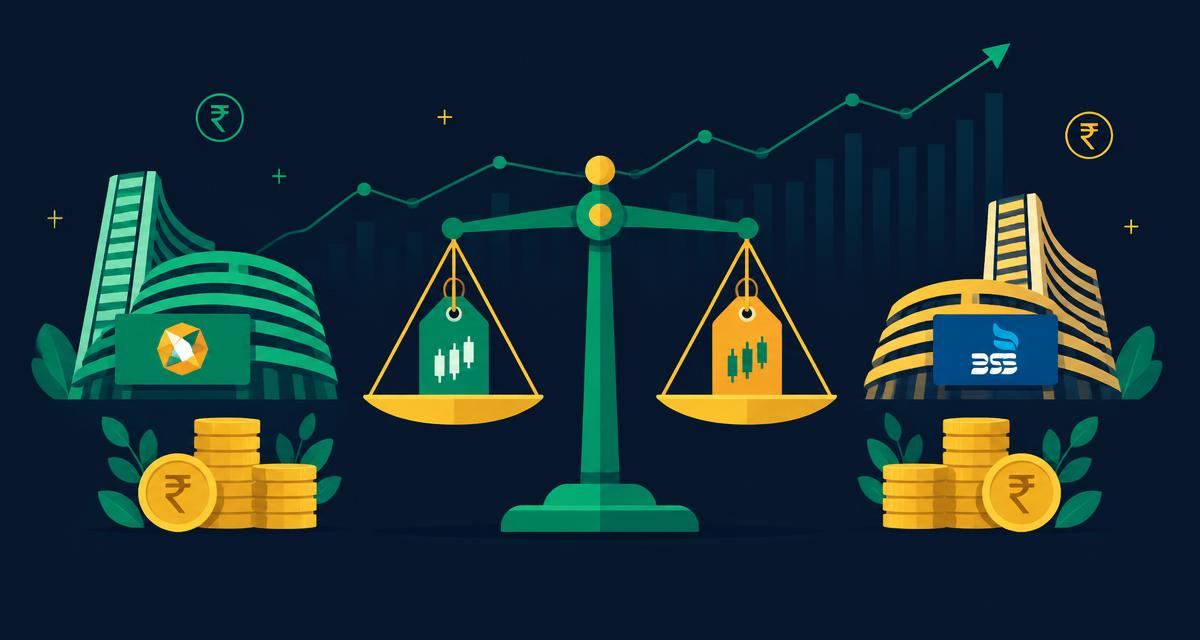
An arbitrage fund simultaneously buys a stock in the cash market and sells it in the futures market (or across two exchanges) when there is a price gap. The gap — usually a fraction of a percent — is locked in as profit, regardless of whether the stock price later rises or falls.
By SEBI rules, arbitrage funds must invest at least 65% of their money in equity and equity-related instruments, which is what earns them equity-fund tax treatment even though their risk profile is closer to a debt fund.
How Arbitrage Funds Make Money: A Worked Example
Suppose Reliance trades at these prices on the same day:
| Market | Price |
|---|---|
| Cash market (buy today) | ₹2,500 |
| Futures market (sell for next month) | ₹2,515 |
| Locked-in gap | ₹15 (0.6% for the month) |
The fund buys at ₹2,500 and simultaneously sells a futures contract at ₹2,515. On expiry day, both prices converge — it does not matter where:
- If Reliance rises to ₹2,600: the cash holding gains ₹100, the futures position loses ₹85 → net ₹15
- If Reliance falls to ₹2,400: the cash holding loses ₹100, the futures position gains ₹115 → net ₹15
The ₹15 is locked in either way. Annualised, a 0.6% monthly gap works out to roughly 7%+ per year — before costs.
Arbitrage Funds vs Savings Account vs Fixed Deposit vs Liquid Funds
| Feature | Savings account | Fixed deposit | Liquid fund | Arbitrage fund |
|---|---|---|---|---|
| Typical return (indicative) | 2.5–3% | 6–7.5% | 6–7% | 6.5–7.5% |
| Risk | None | None | Very low | Low |
| Taxation | Slab rate | Slab rate | Slab rate | Equity taxation |
| Lock-in | None | Yes | None | None (exit load ~30 days common) |
| Best for | Daily cash | Fixed horizons | Emergency fund | 3–12 month parking, especially for high tax slabs |
The standout row is taxation. For someone in the 30% tax slab, FD interest is taxed at 30% — a 7% FD becomes 4.9% after tax. An arbitrage fund held over 12 months is taxed as equity LTCG at 12.5% (and only on gains above ₹1.25 lakh a year), so a 7% return keeps roughly 6.1% after tax.
How Arbitrage Funds Are Taxed (FY 2025-26)
- Held under 12 months: Short-term capital gains taxed at 20%
- Held over 12 months: Long-term capital gains taxed at 12.5%, with the first ₹1.25 lakh of equity LTCG per year exempt
Who Should Use Arbitrage Funds?
The Catches You Must Know
- Returns depend on market volatility. When markets are calm and cash-futures gaps shrink, returns drift down toward liquid-fund levels.
- Exit loads. Many funds charge around 0.25–0.5% if you redeem within 15–30 days. Never park money you might need next week.
- Not for very short horizons. For money needed within a month, a liquid fund or savings account is simpler.
- Expense ratios vary. Direct plans typically cost 0.2–0.5%; always choose direct over regular.
How to Invest: A Simple Action Plan
FAQs
Are arbitrage funds safe?
They are among the lowest-risk equity-classified funds because positions are hedged — but they are not guaranteed. Short periods of small negative returns are possible, and there is no deposit insurance like a bank FD.
How much return can I expect from arbitrage funds?
Historically they have delivered roughly 6–7.5% annually, tracking short-term interest rates and market volatility. Treat this as indicative, not promised — returns vary with market conditions.
Arbitrage fund vs liquid fund — which is better?
For money needed within 1–3 months, liquid funds are simpler and steadier. For 3–12 months, arbitrage funds usually win on post-tax returns if you are in the 20–30% slab, thanks to equity taxation.
Is there a lock-in period?
No lock-in, but most funds levy a small exit load (around 0.25–0.5%) on redemptions within 15–30 days. After that, you can redeem freely.
Can I do a SIP in an arbitrage fund?
You can, but arbitrage funds are better suited to lump-sum parking. A more common use is the reverse: park a lump sum here and run an STP into an equity fund.
Sources: SEBI mutual fund categorisation circulars, Income Tax Act capital-gains provisions for FY 2025-26, AMFI fund data — reviewed October 2026.
Disclaimer: This article is for education only and is not investment advice. Mutual fund investments are subject to market risks. Consult a SEBI-registered advisor before investing.
Did you find this useful?